Gold still answers to rates, not Hormuz
Saturday, Nov. 14, 2026, confirmed the same lesson: bullion still answers to the US rate regime first, and Gulf danger only second. The Strait of Hormuz headlines helped cushion the selloff, but higher real yields, a firmer dollar and firmer Fed pricing did the heavy lifting.
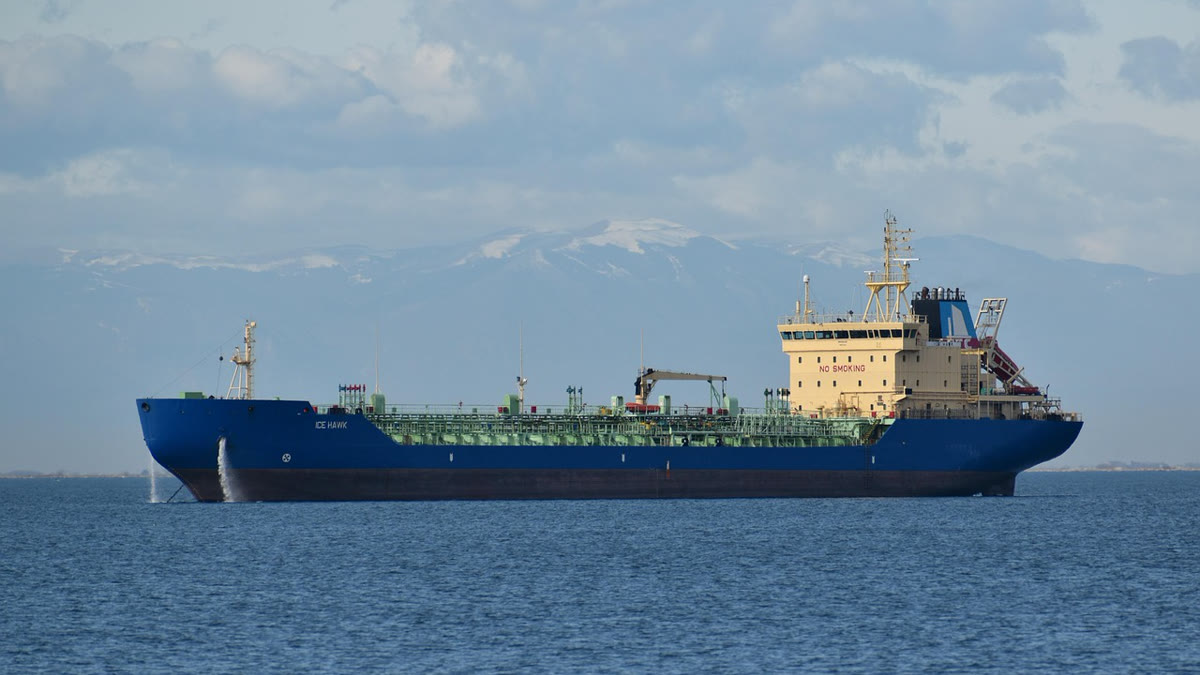
Two burning tankers in and around the Strait of Hormuz should have been gold’s moment. Instead, this week gave us the same lesson again: bullion still trades the US rate regime first, and Gulf danger only second. Iranian outlets reported two tankers exploding south of Hormuz on Nov. 12 and repeated mine-strike claims and shipping warnings through Nov. 14 [H3][H4][H5][H6][H7]. Yet COMEX gold futures fell from $4,073.60 on Nov. 11 to $3,857.50 on Nov. 12, a drop of $216.10, or 5.3%, across the very period when those reports intensified [P2][P3].
The prevailing read is that this break was rate-led, while geopolitics remained a background support for gold rather than the trigger for the latest move [R1][R3][R4][R6][R7]. We think the evidence makes that view broadly right, but not complete enough. Hormuz is helping stop a deeper washout. It is not dictating the turn. The decisive move came from higher real yields, a firmer dollar and a market that pushed Fed expectations back up after a sticky US inflation print [R1][D2][D3].
The Gulf got louder. Gold still went lower.
The timing is the bluntest evidence against the easy haven story. The first report of tanker explosions came at 06:50 UTC on Nov. 12 [H3]. By 15:23 UTC that day, COMEX gold had hit the week’s low at $3,857.50 [P3]. Gold then closed Nov. 12 at $3,886.30, down $113.60 on the session, and was effectively unchanged on Nov. 13 at $3,886.20, even as Iranian warnings kept coming [S2][S3][H4][H5].
That does not mean Gulf risk is irrelevant. It means it was not strong enough to overcome the macro hit. Gold was still $147.40 below its $4,033.70 level just before the first big US yield headline on Nov. 10, a loss of 3.7%, even after the Hormuz escalation [P1][P4]. If shipping danger were truly setting the move, we should have seen a durable bid. We did not.
There is another clue in cross-asset behaviour. Over the past three months, gold’s daily moves have had a stronger inverse link to the US dollar at -0.46 and to the US 10-year yield at -0.30 than any positive link to oil, which sits at -0.34 with WTI [D1]. Gold’s strongest live relationship is not crude at all but silver at +0.85 [D1]. This still looks like a macro precious-metals trade, not an oil-war trade.
The real blow came from inflation and rates
On Nov. 10, the 10-year Treasury yield returned to 5% for the first time in 12 days [H1]. The same day, US CPI rose 0.4% from the previous month, compared with a 0.3% forecast, and core CPI rose 0.3% versus 0.2% expected, even though the annual CPI rate eased to 3.9% from 4.0% [C1][C2][C3]. The annual figure looked softer at a glance. The market traded the monthly heat.
That is why Reuters said gold fell nearly 3% on Nov. 10 as hotter-than-expected CPI lifted the dollar and Treasury yields and reinforced expectations of a bigger Fed move [R1]. By Nov. 12, the 10-year Treasury yield stood at 5.10% and the 10-year TIPS yield, the cleanest measure of gold’s opportunity cost, had climbed to 2.86%, up 0.26 percentage point on the week and marking a fourth straight rise [D2][R6]. That TIPS yield is now at 93% of its past year's span, close to the top of the range that gold has had to fight all year [D2].
Rate expectations moved the same way. The market-implied average Fed rate for the Dec.-Mar. window rose to 4.31%, up 0.20 percentage point on the week, with a 98% chance of staying above the current 3.75%-4.00% range [D3]. Add in a weak long-end funding signal — a 5.441% high yield at the Nov. 12 30-year auction and a bid-to-cover ratio of 2.36 against a 2.44 average over the prior six auctions — and the message is plain: the rate backdrop tightened again [D7].
Geopolitics is supporting gold, just not steering it
The strongest case against us is also real. Gold has deeper support than this week’s selloff suggests. The World Gold Council said Q3 demand by volume was only 1% lower on the year at 1,369 tonnes, but the value of that demand rose 22% to $188 billion, with central banks adding a net 321 tonnes and physically backed ETFs taking in 211 tonnes [R3]. The Council also said global gold-backed ETF demand remained active into early November [R2]. That is not a market with no haven bid.
Positioning says something similar. Managed money’s net long in COMEX gold was 103.6K contracts in the latest CFTC report week, down just 1.9K on the week and sitting only 25% of the way through its past year's span [D4]. The official report is also stale by design, arriving after a three-day lag and only covering the week to Nov. 3 [R5]. So yes, safe-haven and institutional demand are still in the structure. They help explain why gold is not much weaker despite a brutal rise in real yields [R2][R3][D2].
But that is exactly the point. Geopolitics is acting as a floor, not a trigger.
What has to change for Hormuz to count
If we are right, more shipping headlines on their own will not give gold a lasting lift while US real yields remain elevated and Fed pricing keeps drifting higher [D2][D3]. The next durable move up in bullion needs the rate pressure to ease first. Then the same Gulf backdrop that failed to rescue gold this week could suddenly bite much harder.
The near test is not another tanker report. It is whether the Fed story cools. Fed Chair Warsh speaks on Nov. 16, and US retail sales and core retail sales follow on Nov. 17 [C12][C13][C14]. If those events keep yields high, gold will keep struggling to hold a geopolitical premium. If yields roll over, Hormuz stops being background noise and starts becoming fuel.
Key data
| Measure | Value | Source |
|---|---|---|
| COMEX gold futures low | 3,857.50 | COMEX gold futures (GoldSquawk data) |
| 10-year TIPS yield | 2.86% | Federal Reserve Bank of St, via GoldSquawk data |
| Market-implied average Fed rate | 4.31% | Federal Reserve Bank of Atlanta, via GoldSquawk data |
| Managed money net long | 103.6K | CFTC Commitments of Traders, via GoldSquawk data |
| 30-year auction high yield | 5.441% | US Treasury, via GoldSquawk data |
Primary sources
- World Gold Council · Central bank buying and ETF inflows support gold demand in Q3
- Federal Reserve Board · H.15 - Selected Interest Rates (Daily) - November 13, 2026
- World Gold Council · Gold ETF: Stock, Holdings and Flows
- Commodity Futures Trading Commission · Commitments of Traders
- GoldSquawk data: Intermarket correlations; Opportunity cost of gold (Federal Reserve Bank of St); Fed rate expectations (Federal Reserve Bank of Atlanta); US Treasury auctions (US Treasury)
General market commentary only. Not financial advice.