Gold has cut the crowd, not cleared it
Sunday, Nov. 15, 2026 — Gold has broken the big figure, but this selloff has not delivered the clean reset many want to see. The macro driver is right; the claim that positioning has already been fully cleaned out is not.
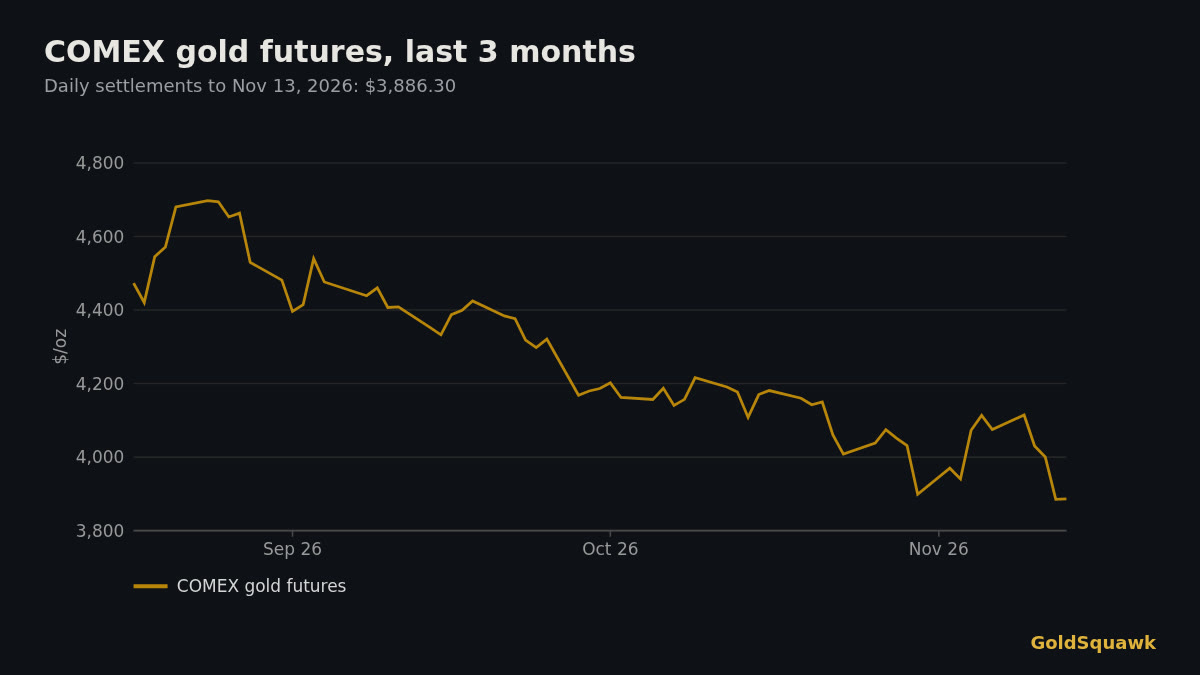
Gold has broken the big figure, but we do not think this selloff has delivered the clean reset many want to see. COMEX gold fell from $4,004.60 at 01:16 UTC on Nov. 12 to $3,857.50 by 15:23, a $147.10 drop, or 3.7%. By the Nov. 12 close, futures were down $113.60 on the day at $3,886.30, a 2.84% slide. That is violent price action. It is not proof that the long has been fully purged.
The prevailing reading is that this is a leveraged-futures unwind driven by a tougher Fed path, but not a full capitulation because ETF flows have been calm and managed money is still net long. The World Gold Council says gold weakness increasingly reflects a repricing of the Fed’s expected rate path, a rotation into bonds and selling by leveraged investors, while US gold ETF flows have been “fairly benign” and stickier holders are more positive. Kitco has framed the break of $4,000 as a critical technical failure tied to persistent inflation, rising odds of a Fed hike and the risk of more liquidation toward $3,900. We think that view is only half-finished. The macro driver is right. The conclusion that positioning has already been cleaned out is not.
The tape says liquidation, not finality
The market action fits a de-grossing phase. Gold was $3,991.40 just before the first wave of break-$4,000 headlines on Nov. 11. It briefly traded back up to $4,004.60 a few hours later, then failed hard into $3,857.50. That pattern looks less like calm repricing by long-term holders and more like leverage being cut.
But the follow-through also tells us something else. After Thursday’s collapse, futures closed Friday at $3,886.20, virtually unchanged on the day. That came even though US producer prices were not hotter than feared: headline PPI rose 0.3% in October against a 0.4% forecast, and core PPI rose 0.3%, in line with expectations. US jobless claims were 200,000, above the 194,000 forecast. In other words, gold did not need another inflation shock to stay weak. Once a leveraged unwind is under way, slightly softer data often only stop the bleeding. They do not end it.
That is why the World Gold Council’s explanation is useful but incomplete. Yes, higher rate expectations and bond competition are weighing on gold. But the inability to bounce on less-hawkish data suggests there is still position reduction happening inside that macro story.
The futures crowd is smaller, not gone
The cleanest evidence sits in CFTC positioning, even with its lag. As of Nov. 3, CFTC data compiled by GoldSquawk showed the broader COMEX gold speculative net position was 179,500 contracts after eight straight weekly declines, down 42,700 contracts from 222,200 on Aug. 18, a fall of 19.2%. That is a real de-grossing.
It is not capitulation. CFTC data showed managed money was still net long 103,614 contracts, with 122,283 longs against 18,669 shorts on the same date. That is roughly 6.5 longs for every short, using 122,283 divided by 18,669. CFTC data showed total COMEX gold open interest was 399,169 contracts, so managed money’s net long was still about 26% of open interest, using 103,614 divided by 399,169. That is not a market stripped of bullish exposure.
Nor had hedge funds already stopped selling before the break. Managed money net length slipped by another 1,900 contracts in the latest week to Nov. 3. The broader speculative net fell 6,900 contracts in that week. The report is static and only captures each Tuesday’s position snapshot, then gets released later. So it does not include the worst of the Nov. 11-12 washout. That is the strongest case against our view: the market may now be cleaner than the official data show. Fair enough. But even allowing for heavy selling after Nov. 3, the last official picture was still clearly net long, not neutral.
ETF calm is support later, not relief now
If this were a full investor exodus, we would expect much nastier fund outflows. We do not have them. SPDR Gold Shares data showed GLD held 1,040.7 tonnes on Nov. 12, down 13.5 tonnes over a month and 5.9 tonnes over a year. Over the four weeks to Nov. 12, GLD holdings fell 13.0 tonnes, or 1.2%, while COMEX gold futures dropped 6.8%, from $4,170.10 to $3,885.30. That is selling, but it is mild beside the price move.
The weekly flow picture is calmer still. GLD and GLDM together saw inflows of 3.2 tonnes in the latest week, though the four-week total was still an outflow of 6.3 tonnes. Over 26 weeks, those two funds have taken in 28.0 tonnes. At the global level, World Gold Council data showed global gold ETF holdings were 4,275 tonnes at the end of October, up 19 tonnes on the month, with flows of $2.7 billion. That does not rescue the price now. It does tell us that strategic holders have not joined the futures liquidation in size.
That cuts both ways. It means gold can stay heavy if real yields and the dollar keep pressing, because the futures long is not obviously empty yet. But it also means there is fuel for a rebound later. If the macro squeeze eases, there are still longs to re-risk and there has not been the kind of broad fund abandonment that usually poisons rallies for months.
The next test is not a chart level
If we are right, the important question is not whether $3,900 or even $3,800 gets printed next. Kitco says analysts are already eyeing both zones after the break of $4,000. The bigger question is whether next week’s US macro and Fed communication deepen the rates repricing enough to force the remaining leveraged length out.
The immediate tests are Fed Chair Warsh on Nov. 16, US retail sales on Nov. 17 and the FOMC minutes on Nov. 18. If those keep rate expectations climbing, this unfinished de-grossing can keep dragging gold lower. If they do not, the same evidence that makes us cautious on the downside now, a still-positive futures long and restrained ETF selling, is exactly what can power a bounce. Gold has cut the crowd. It has not cleared it.
Key data
| Measure | Value | Source |
|---|---|---|
| Gold drop from the intraday high | 3,857.50 | COMEX gold futures (GoldSquawk data) |
| Nov. 12 settlement fall | $3,886.30 | GoldSquawk settlement data |
| Speculative net position | 179.5K | CFTC Commitments of Traders, via GoldSquawk data |
| GLD holdings | 1,040.7 t | SPDR Gold Shares, via GoldSquawk data |
| Weekly GLD and GLDM flows | +3.2 t | SPDR Gold Shares, via GoldSquawk data |
Primary sources
- World Gold Council · WMM_2 Nov 2026 Leveraged Repricers
- CFTC · CFTC Commitments of Traders Long Report - Other (Combined)
- CFTC · Commitments of Traders | CFTC
- CFTC · CFTC Commitments of Traders Report - CMX (Futures Only)
- GoldSquawk data: Speculative positioning (CFTC Commitments of Traders); Positioning by trader type (CFTC Commitments of Traders); Gold ETF holdings (GLD) (SPDR Gold Shares); Gold ETF flows (SPDR Gold Shares)
General market commentary only. Not financial advice.